


Vehicle affordability has become a defining battleground for dealership finance offices. With interest rates hovering around 7% and average new-vehicle loans crossing $44,658, consumers are carrying higher lifetime debt than ever before. In response, Congress enacted the qualified passenger vehicle loan interest deduction under H.R. 1, permitting eligible taxpayers to deduct up to $10,000 annually in interest on qualifying new, American-assembled vehicles purchased between 2025 and 2028.
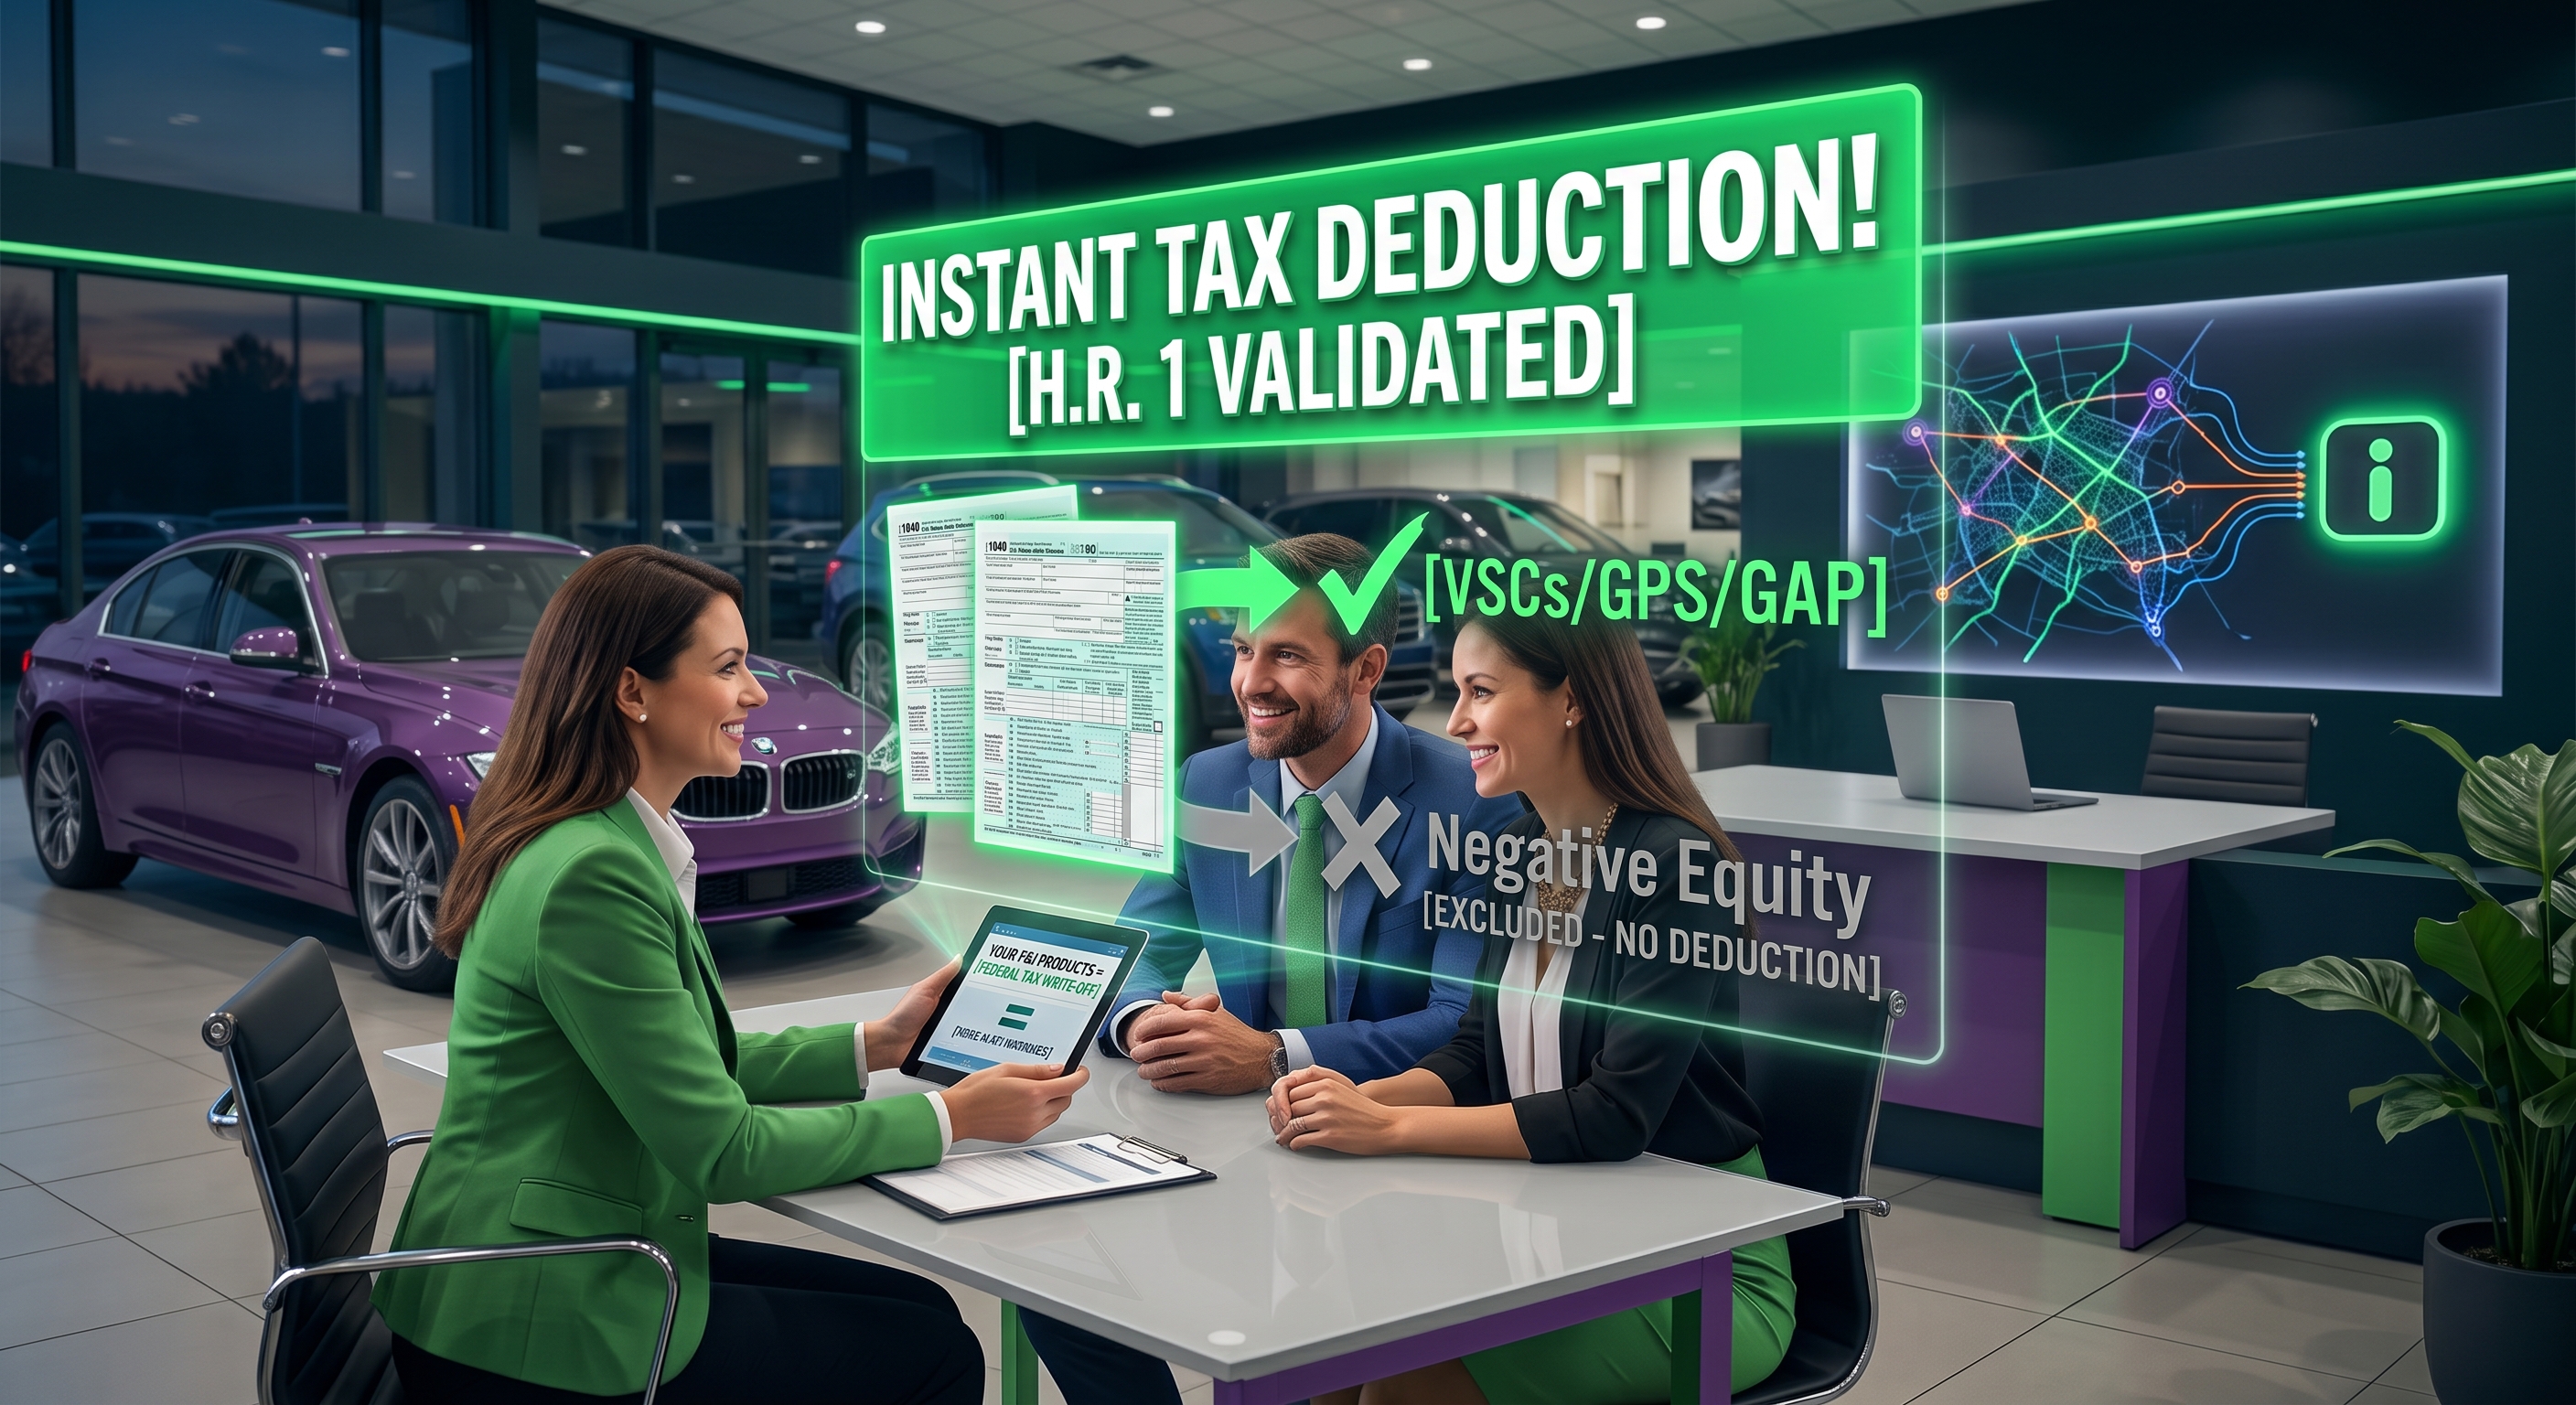
On September 8, 2026, the Internal Revenue Service released its finalized regulations. While the IRS rebuffed industry efforts from NADA and AFSA to make rolled-over trade-in debt tax-deductible—ruling that negative equity belongs to the previous vehicle—the agency granted a decisive victory for franchise finance departments: interest paid on customarily financed protection products, warranties, and point-of-sale accessories is 100% tax-deductible.
Why Connected GPS Solutions Like Ikon Are Fully Deductible
For modern dealerships equipping inventory with connected telematics, the final rule provides unambiguous regulatory support. The IRS framework explicitly protects two categories that directly house Ikon Technologies: vehicle protection products and vehicle-related accessories financed at delivery.
Because Ikon functions both as an installed physical theft recovery device and an ongoing digital maintenance platform, buyers who finance an Ikon package can deduct the interest accrued on that protection right alongside their core auto loan interest on IRS Form 1040, Schedule 1-A.