Ikon for F&I Departments

OUR PROMISE
The Ikon Way enables you to:
  • Increase PVR
  • Eliminate cancellation risk
  • Wrap and upsell to term
Average PVR Boost
$323 + Wrap
per sale
Cancellation Rate
0%
vs. 25% for many paper products
Theft Warranty Benefit
$10,000
$8000 of which must be spent with you
Explore our features and solutions
Shut Down THE IKON LOOP
OUR DIFFERENCE

Secure the backend. Lock in your gross.

Because your profit belongs on the books permanently. A useful app and a $10,000 theft warranty customers keep, not GAP/VSC they cancel. 30% average term wrap rate.

01

Attractive, Tangible Consumer Product

Ikon is just easier to sell and wrap than other F&I products. It’s a truly useful app and a $10,000 theft benefit, $8,000 of which is only spendable at the originating dealer. The term can be wrapped at F&I to protect the customer's new vehicle for the entire term of their loan or lease.

See how your dealership compares 👇

What is your F&I department’s single biggest profit-margin leak?

A product with real benefit for you and them

When you deliver a truly useful theft recovery and family safety app paired with a $10,000 benefit, you drive a retention rate that legacy products simply can't touch. Ikon is your daily tool to help your F&I team sell easier, secure lifelong loyalty, and ensure that when it’s time for their next car, they are coming back to you.

Want to learn more?

Ikon Platform DEMO

See How Ikon Can Boost PVR by $323 and Drive 32% more ROs

Get a FREE Demo

Ikonic Dealers' Webinar

32%+ average service reminder response rate. 74% higher chance that a service customer will buy their next vehicle from you.

Watch the Webinar

Zero Chargeback Risk: Secured Gross

Unlike traditional products such as Vehicle Service Contracts (VSCs), which are legally classified as service contracts and subject to mandatory refunds in 46 states, Ikon is itemized as a permanent accessory or dealer-installed option on the sales addendum. Because it is a physical, integrated asset rather than a promise of future service, the revenue is instantly realized and locked into the front-end gross profit at the point of sale.

02

Master the Chargeback Crisis

Never watch your hard-earned PVR disappear into thin air because of an early payoff. When you sell a non-cancellable permanent accessory instead of a service contract, you remove the chargeback risk that can typically cost dealers 25% of their back-end income.

PROTECT YOUR BACK-END GROSS

F&I Profitability Secured

Stop watching your profit evaporate. We transform your back-end from a house of cards into a secured profit center with non-cancellable PVR that stays on the books. Ready to lock in your gross?

Non-Cancellable Gross Profit

Unbreakable PVR
Unlike service contracts subject to mandatory refunds, Ikon is an integrated permanent accessory. The profit you book today stays on the ledger tomorrow, completely immune to the industry’s 25% chargeback crisis.

Instant Income Realization

Accelerated Funding
Eliminate the "Reserve Holdback Penalty." Because the Ikon program is non-cancellable, you can demand 100% of your profit from the lender instantly, by passing the 180-day "frozen capital" cycles common with other products.

Great Wrap Opportunity

Additional PVR Uplift
If your dealership sells Ikon as a front-end add, F&I can still sell a term wrap to match the customer's loan or lease. That gives the customer vital protection for their entire ownership experience.

Customer Testimonials

Discover more testimonials from our customers. Contact us for more details about our onboarding and success KPIs.

Stanley Automotive Group

Ikon Technologies has provided help beyond measure. It doesn't make a difference what time of day or night - I can get an answer to a question if we have an issue.

P. Healy, Executive VP / Group Operations & Finance Director
Texas
Stanley Automotive Group
Spitzer Auto World

On multiple occasions, Ikon has provided instant clarity whenever we had doubts about a vehicle's whereabouts. In one instance, an auditor couldn't find a unit, but we opened the Ikon Portal, pinpointed its location, and sent a photo and VIN to the auditors - leading to a clean audit.

R. Jambor, Inventory & Floorplan Finance Controller
Florida
Spitzer Auto World

Frequently Asked Questions

How do you sell Ikon to cash buyers and commercial fleet accounts?

Cash buyers and fleet accounts routinely turn down mechanical breakdown coverage, GAP, and standard F&I products. However, business owners and cash buyers still care about tracking their vehicles, monitoring employee driving habits, setting boundary alerts, and protecting their investment against theft. F&I managers present Ikon Connect as an asset security and fleet tracking tool, capturing high-margin sales on cash deals where F&I penetration is usually zero.

How does Ikon fit within lender loan-to-value (LTV) advance limits?

Lenders place strict caps on loan-to-value advances, often limiting backend warranties and accessories to 115% to 125% of vehicle invoice or book value. When F&I managers try to pack multiple expensive warranty products, lenders reject contracts for exceeding advance caps. Because Ikon is priced cleanly on consignment, it fits comfortably within standard LTV room without blowing up lender approvals.

How do top F&I managers overcome the "my car already has an app" objection?

When a customer mentions that their vehicle already comes with a factory app, experienced F&I managers explain that factory systems are designed for basic convenience, not rapid recovery. Automakers require filed police reports and call center paperwork before tracking a vehicle, and they offer zero financial payout if the vehicle is stripped. In contrast, Ikon provides responding police officers with instant live tracking in any mobile browser, includes an unrecovered theft warranty of up to $10,000, and has zero monthly subscription fees.

How does showing the app at delivery feed business into our service department?

During the F&I handoff, the business manager makes sure the customer is logged into their dealer-branded Ikon Connect app. Showing the buyer how the app displays upcoming factory maintenance alerts and includes 1-tap service booking bridges the gap between sales and fixed ops, building a habit that drives customer-pay service visits for years to come.

Why doesn't consignment inventory create debt on the store's balance sheet?

Accounting guidelines require unsold vendor hardware stored in parts rooms or pre-loaded on lot cars to be booked as an asset and tracked against accounts payable. Because Ikon devices are delivered on true consignment, there is no wholesale invoice until the vehicle is retailed. Store controllers don't have to carry extra inventory debt, manage hardware depreciation, or spend time doing parts room counts.

What happens to the device if a car goes to auction or a lease unwinds?

When a vehicle gets sent to wholesale auction or a lease deal unwinds, dealers using traditional tracking hardware lose whatever money they spent on that box. Because Ikon operates on consignment and waives unsold units once sales thresholds are reached, the store incurs no penalty if a car is wholesaled without the product. If preferred, prep staff can pull the hardware in under 5 minutes to install it on fresh inventory.

Why do customers buy an app-based product more easily than a traditional paper warranty?

Car buyers are often skeptical of long paper warranty contracts packed with fine-print exclusions. In contrast, a smartphone app provides immediate, visible utility. Customers instantly understand the value of live GPS tracking for teen drivers, battery health notifications, speed alerts, and parking locators on their phones. Because the value is clear from the moment they open the app, F&I teams regularly see closing rates of 40% to 50% across finance and lease deals.

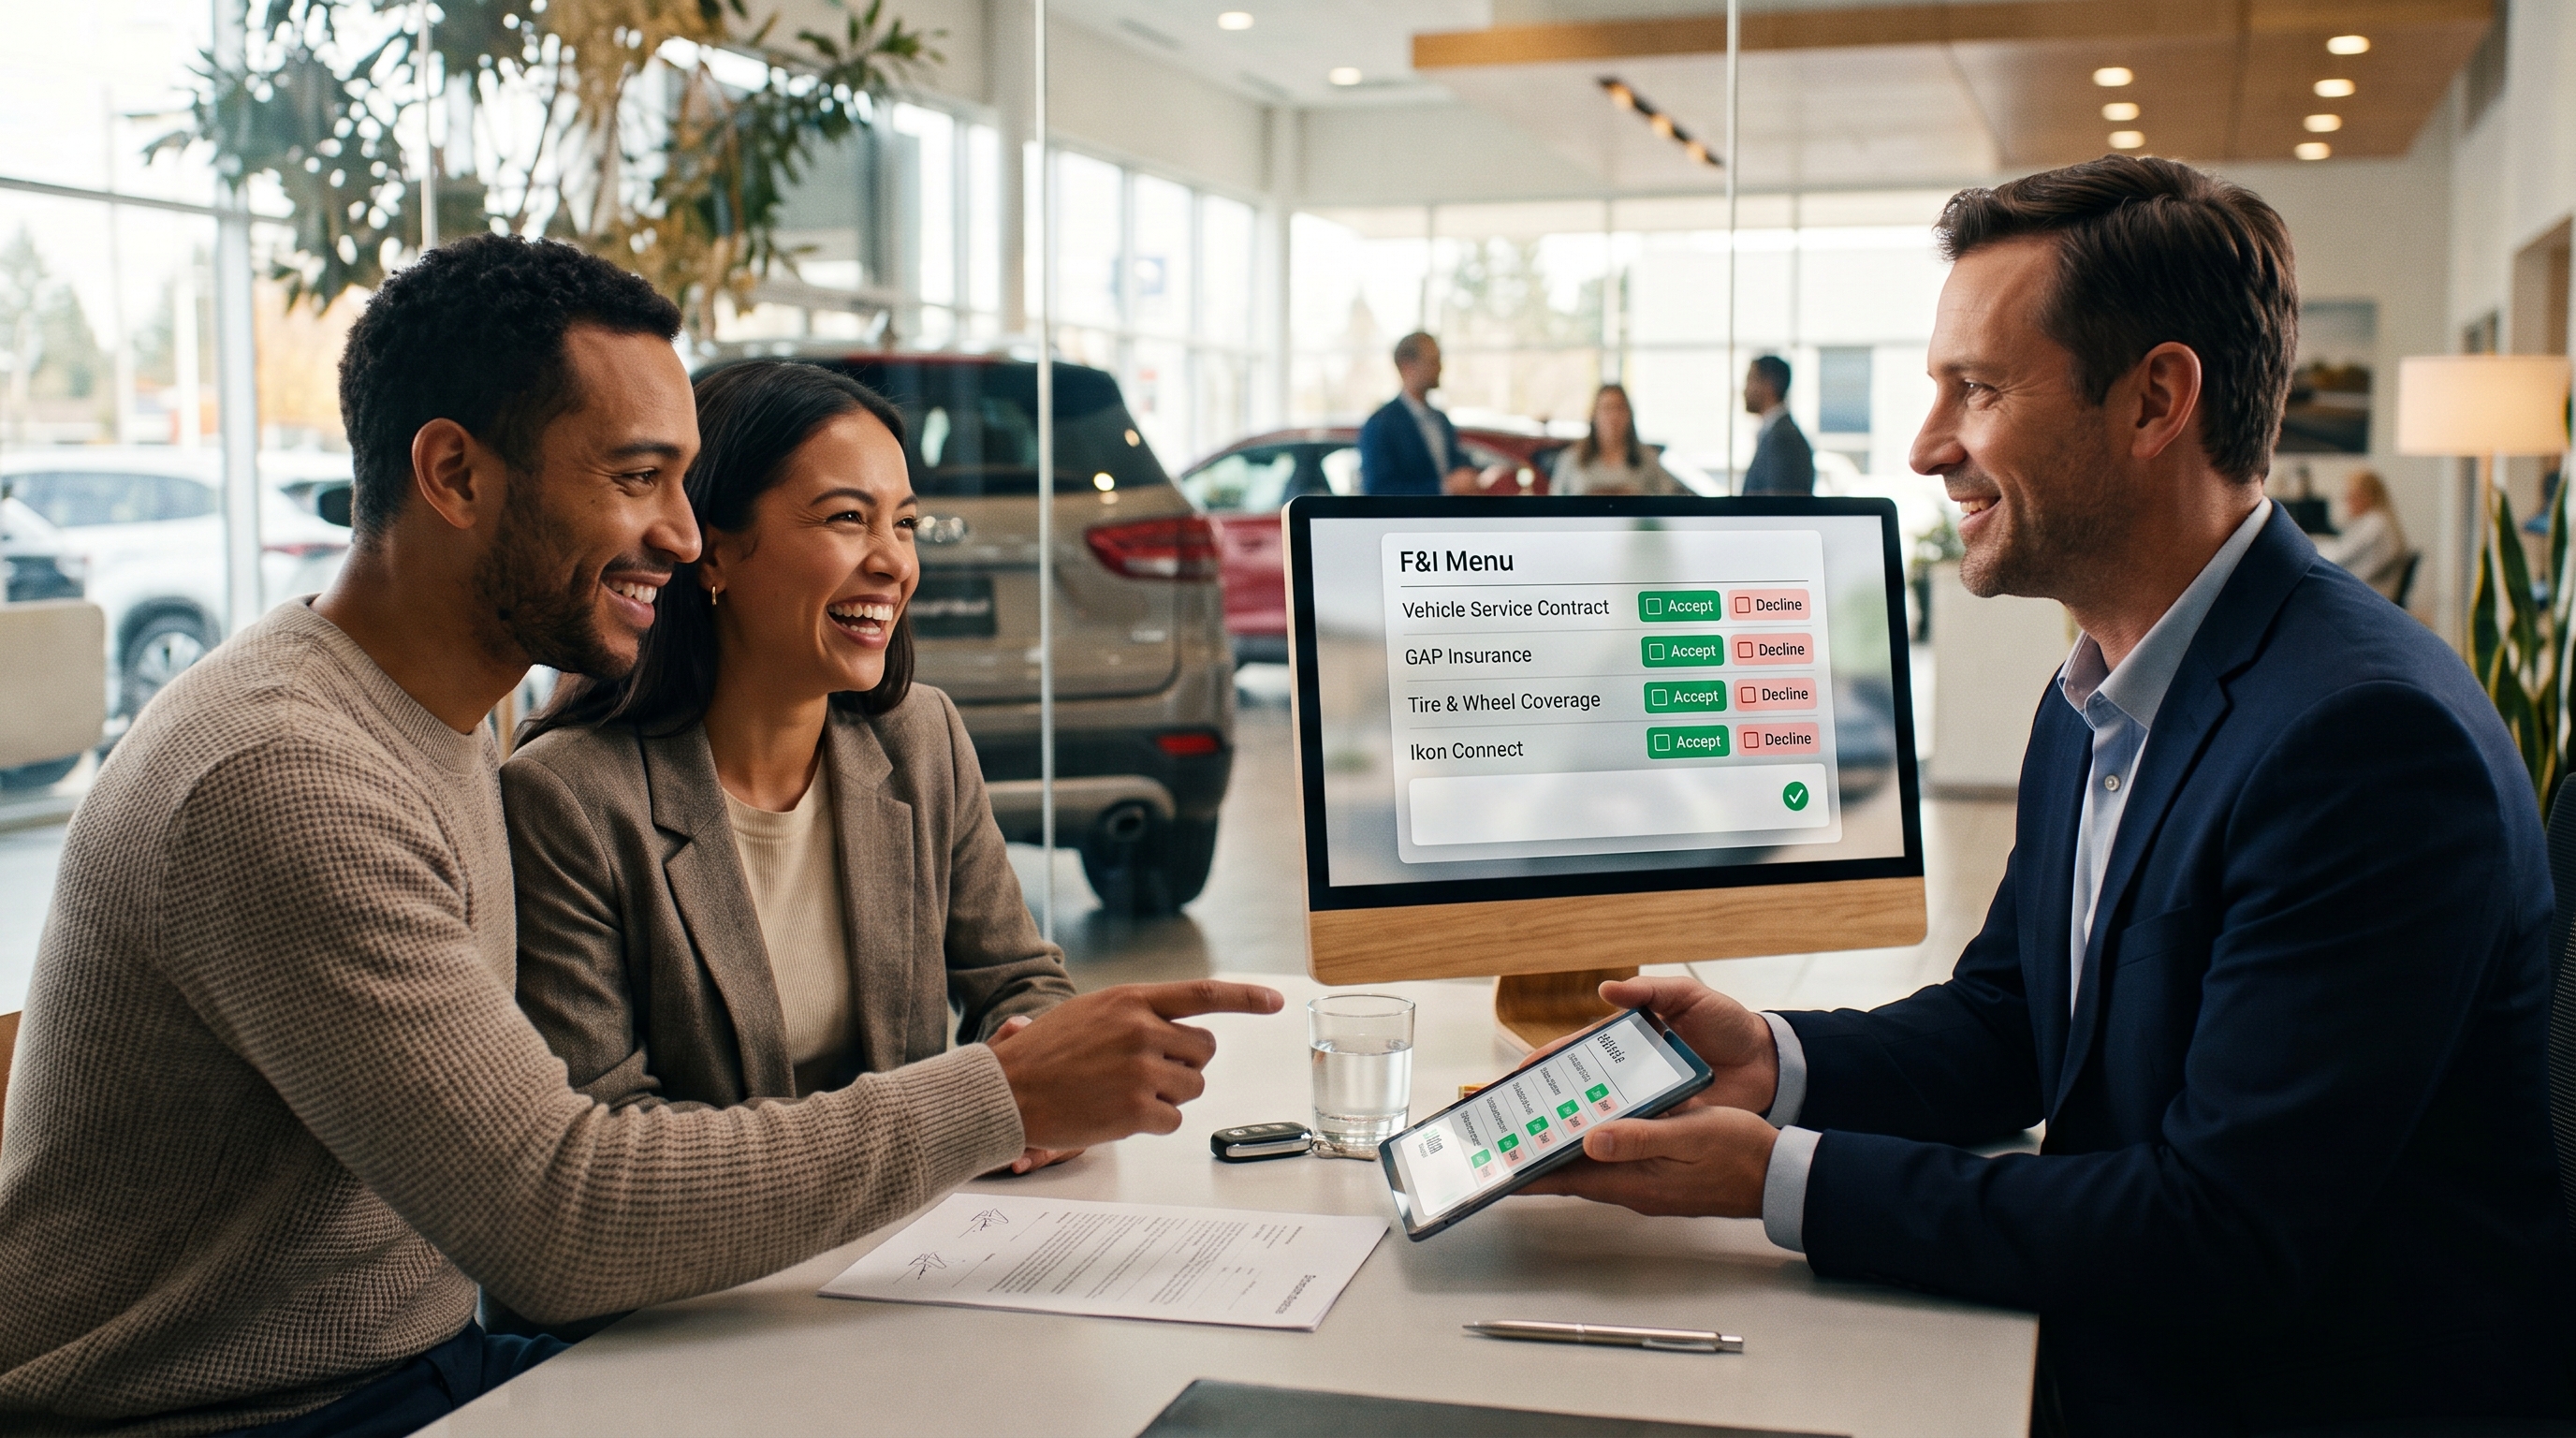
How does Ikon connect with digital F&I menu software like Darwin, CDK, and Reynolds?

Ikon integrates directly via API with major digital menu providers, including Darwin Automotive, MaximTrak, CDK Global, DealerTrack, and Reynolds & Reynolds. It pushes product descriptions, pricing options, term-wrap lengths, and warranty contracts onto the menu with a single click, eliminating manual data entry and preventing contracting mistakes.

What happens if a customer declines Ikon on the menu—are there privacy issues?

If a car buyer chooses not to buy the Ikon Connect package on the menu, the F&I manager marks it declined in the system. The platform immediately disables consumer tracking feeds for that VIN, preventing any unauthorized tracking and protecting the store from consumer privacy disputes. The device stays dormant, maintaining internal inventory records without gathering customer data.

Can commercial and business buyers write off financed telematics accessories?

Under federal tax guidelines governing commercial vehicle installment financing, interest and depreciation expenses on dealer-installed vehicle tracking and protection equipment bundled into the vehicle purchase loan can qualify for commercial tax deductions. F&I managers can highlight this distinction when structuring commercial, fleet, or 1099 contractor deals, showing business buyers how financing installed telematics can improve their bottom line.

How do state insurance discount laws help F&I managers close the product?

States like California, Texas, Florida, New York, Illinois, and Pennsylvania have statutory rules requiring auto insurance companies to offer comprehensive premium discounts of 5% to 25% for vehicles equipped with certified stolen vehicle tracking systems. Ikon generates an Insurance Savings Certificate when the deal is printed. F&I managers can hand this certificate to payment-conscious buyers, showing them how monthly insurance savings help offset the cost of the product.

How does Ikon keep menu presentations clean and compliant with FTC Safeguards and CARS Act rules?

Regulators are focused on transparent pricing, cracking down on payment packing and unauthorized add-ons. Ikon integrates directly into major digital F&I menu software, allowing F&I managers to present it clearly as a distinct, pre-installed asset protection accessory. The menu documentation outlines the package's two components (the connected car app and the $10,000 theft warranty), giving you an auditable record of clear, voluntary consumer consent.

How is the $10,000 theft protection warranty split between the customer and the dealer?

The $10,000 theft protection warranty is designed to protect the customer from financial loss while ensuring replacement vehicle revenue returns to your store. The warranty pays up to $1,000 directly to the customer to cover their comprehensive auto insurance deductible, plus up to $1,000 for emergency rental car expenses. The remaining $8,000 is issued as a replacement credit that must be used back at your dealership toward purchasing a replacement car. This structure protects the buyer from negative equity and keeps the replacement car deal at your store.

How does term-wrapping Ikon to match the finance contract create back-end profit?

Beyond the standard multi-year connected package, F&I managers can extend the connected car telematics and theft coverage term to match the buyer's full financing term or lease duration. Dealerships average a 30% attachment rate on term-wraps, generating extra back-end gross profit while keeping the customer connected to the dealership for the life of the loan.

Where does the $323 average PVR increase come from?

The overall financial return from the Ikon program per retail deal combines front-end addendum gross, term-wrap options, and captive reinsurance profits. Total yield = base addendum margin ($323 avg) + term-wrap markup + Captive Underwriting. Because the hardware is supplied on consignment and unsold units are forgiven once the store hits 40% penetration, the store has no upfront hardware cost. The spread between program cost and your retail addendum price is pure margin, delivering a verified average front-end PVR lift of $323 per contract.

How does Ikon avoid lender reserve holdbacks?

Indirect auto lenders often protect themselves against contract cancellations by enforcing reserve holdback policies. Under standard 75/25 lender holdback rules, the finance company holds back up to 25% of the store's earned finance and backend reserve for up to 180 days to cover potential cancellations. Because Ikon is financed as an installed accessory on the vehicle's capital balance, lenders fund 100% of the contract amount upon contract approval without holdbacks, putting cash into the store immediately.

How does Ikon eliminate chargeback liability for F&I?

F&I departments routinely deal with a 20% to 25% cancellation rate on paper warranties due to early trade-ins, insurance write-offs, and refinancing within the first three years. Those cancellations generate chargebacks that hit F&I commissions and reduce the store’s reserves. Because Ikon is a non-cancellable accessory, the gross profit is 100% earned at the time of sale. The store carries $0 chargeback liability, protecting F&I pay plans and keeping reserve gross on the books.

Why is Ikon treated as a non-cancellable accessory instead of a cancellable service contract?

Traditional F&I products like vehicle service contracts, prepaid maintenance, and GAP coverage are legally classed as insurance or service contracts. In 46 states, state regulations mandate that if a customer trades in, pays off, or refinances their car early, the unearned portion of that contract must be refunded on a pro-rata basis. Ikon is sold and classified as a physical, dealer-installed accessory. It is listed on the vehicle addendum and sales contract as permanently installed physical equipment. Because it is physical hardware rather than a paper service policy, it is not subject to statutory early cancellation or refund rules.

Discover more Finance & Insurance tips on our blog…

Read More on the Blog